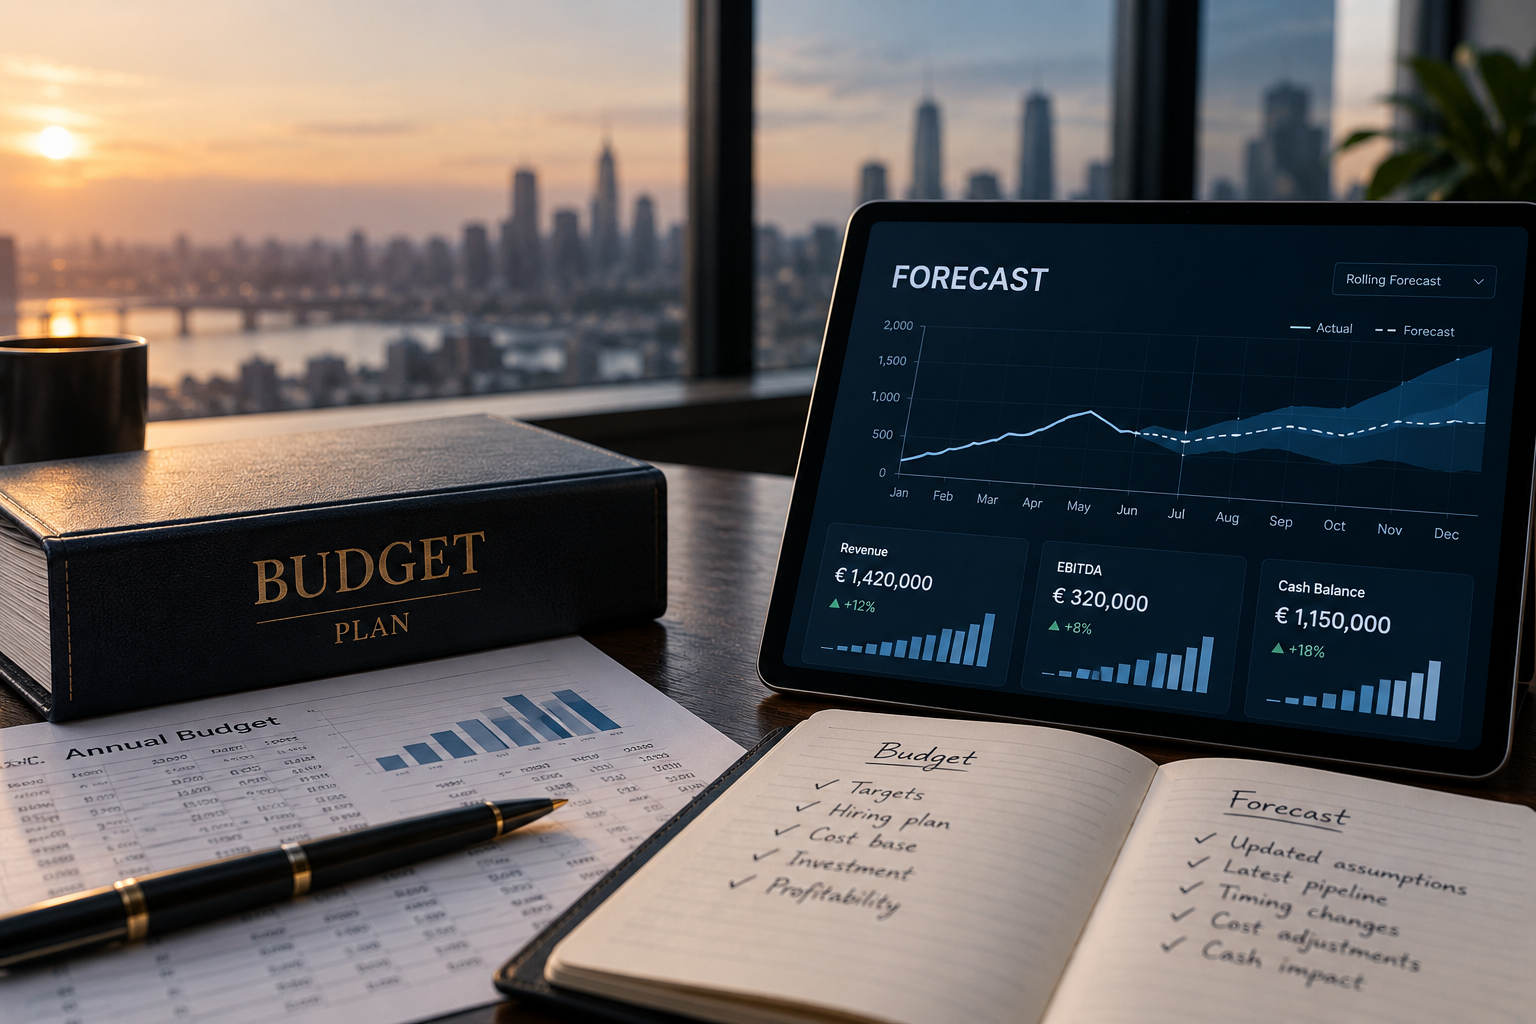
Budgets and forecasts are often treated as interchangeable, but they serve fundamentally different purposes. A budget establishes what a business intends to achieve. A forecast tells management what, based on the information available today, is actually likely to happen.
The distinction may seem academic when a business is small and relatively predictable. As complexity increases, however, it becomes critical. A budget prepared at the beginning of the year reflects the assumptions that existed at that point in time: expected revenue, planned hiring, operating costs, investment and profitability. Those assumptions begin changing almost immediately.
Customers sign later than expected. Recruitment takes longer. Costs increase. Pricing changes. New opportunities emerge. Some investments are postponed while others become necessary. None of this means the original budget was poorly prepared; it simply means the business has moved on.
A useful forecast moves with it.
The Budget Remains the Baseline
The fact that circumstances change does not make the budget irrelevant. It remains an important reference point for understanding performance and accountability. Comparing actual results with budget helps management identify where the business is performing differently from plan.
But variance analysis should be the beginning of the conversation, not the end of it.
If revenue is €200,000 below budget, management needs to understand why. Perhaps sales volumes are lower than expected, contracts have been delayed, pricing has changed or customer churn has increased. More importantly, management needs to determine whether the variance is temporary or whether it changes expectations for the months ahead.
Simply reporting that revenue is 8% below budget describes the past. Understanding the cause and incorporating its implications into the forecast helps management decide what to do next.
The Forecast Is the Current View
A forecast should reflect the best information available to the business today. If hiring has been delayed by three months, the expected cost base should change. If a significant customer contract has been signed, its expected revenue, costs and cash impact should be incorporated. If sales are consistently developing below plan, the forecast should acknowledge that rather than continue assuming the original budget will somehow materialize.
This is why a forecast should not be judged primarily on whether it eventually proves perfectly accurate. No financial model can predict the future with certainty. Its purpose is to give management a sufficiently reliable view of the road ahead to make better decisions while there is still time to act.
That might mean slowing recruitment, accelerating a commercial initiative, delaying an investment, addressing a developing cash constraint or reallocating capital toward a better-performing part of the business.
The value is not in producing another spreadsheet. It is in creating an early-warning and decision-making system.
From Reporting to Decision Support
This distinction also illustrates the difference between financial reporting and strategic finance.
Management needs to know what happened. But as a business grows, it increasingly needs to understand what those results mean for the future.
A strong finance function therefore connects three perspectives: what the business originally planned, what has actually happened, and what is now expected to happen. Looking at any one of those in isolation provides an incomplete picture.
A business should not discover a cash problem when the cash is almost gone, nor should management reach the end of the year before realizing that a profitability target became unrealistic months earlier.
The budget tells you where you intended to go. The forecast tells you where you are currently heading. Good financial management requires both.
Springboard Advisory provides fractional CFO and strategic finance support to founder-led and growth-stage businesses.